Shared Intelligence, Identical Strategy: The Hidden Cost of Industry-Wide Research Dependency
The Illusion of Informed Strategy
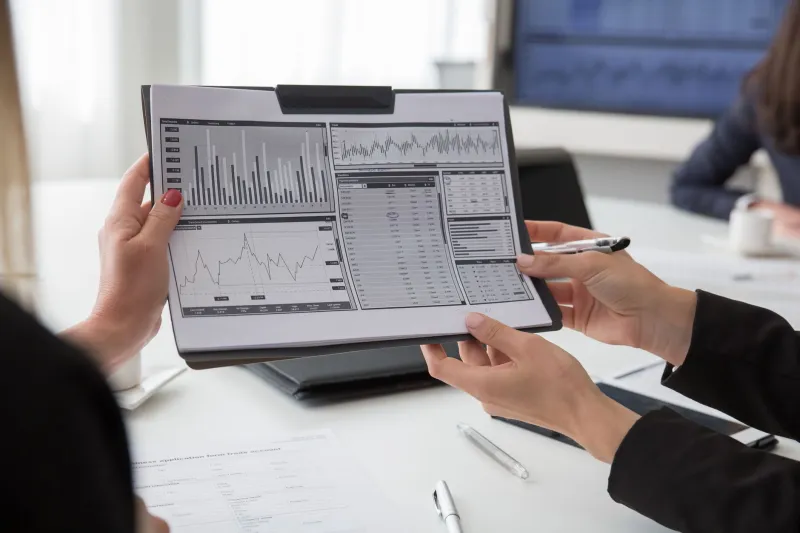
There is a particular kind of confidence that descends upon a leadership team after reviewing a comprehensive industry report from a well-regarded research firm. The data is thorough, the visualizations are polished, and the projections carry the quiet authority of institutional credibility. What that confidence rarely accounts for is a straightforward and consequential reality: your three closest competitors reviewed the same document last quarter.
This is not a peripheral concern. Across U.S. corporate boardrooms, strategic planning cycles are increasingly anchored to a surprisingly narrow set of syndicated data sources. The major market intelligence publishers—firms whose subscription revenues depend on broad appeal—design their outputs to be relevant to the widest possible audience. That design imperative is, by definition, incompatible with producing intelligence that gives any single subscriber a meaningful edge.
The result is a form of strategic convergence that organizations rarely recognize from the inside. Executives interpret shared data as market consensus. Market consensus informs resource allocation. Resource allocation produces nearly identical competitive postures. And then, when differentiation fails to materialize, leadership teams commission more research—often from the same providers—to understand why their strategy is underperforming.
How Syndicated Research Creates Strategic Monocultures
Syndicated research is not inherently flawed. For understanding broad macroeconomic trends, regulatory shifts, or aggregate consumer demographic patterns, third-party reports serve a legitimate and efficient function. The problem is not the research itself—it is the degree to which organizations treat it as a sufficient foundation for competitive strategy.
Research providers operating at scale face a structural tension. To justify enterprise subscription pricing across a diverse client base, their findings must resonate with manufacturers, distributors, retailers, and service providers simultaneously. Insights that are genuinely provocative, sector-specific, or actionable for a narrow audience tend to be smoothed out in favor of conclusions that feel broadly applicable. Contrarian signals—the early indicators that something fundamental is shifting beneath the surface of a market—rarely survive the editorial process of a report designed to avoid alienating any segment of its readership.
The consequence is that the intelligence most likely to generate competitive advantage is precisely the intelligence most likely to be absent from the reports your organization and its competitors are jointly consuming.
Identifying Your Proprietary Research Gaps
Breaking free from consensus intelligence begins with a candid internal audit. Organizations should systematically examine the sources underpinning their current strategic assumptions and ask a pointed question: what percentage of this intelligence is available, in substantially similar form, to our direct competitors?
For most U.S. enterprises, the honest answer is uncomfortable. The bulk of strategic research inputs—consumer sentiment surveys, market sizing estimates, category growth projections—originates from a small cluster of research publishers whose client lists read like an industry directory. If your competitors have access to the same data architecture, your strategy is being built on a shared foundation.
Proprietary research gaps typically emerge in three areas. First, primary customer intelligence: direct research conducted with your specific customer base, at sufficient depth and frequency to reveal preference patterns that aggregate surveys obscure. Second, behavioral data interpretation: the translation of operational and transactional data into forward-looking signals, rather than backward-looking performance metrics. Third, competitive edge cases: research into the market segments, geographic pockets, or customer cohorts that are too small or too specific to appear in broad industry analyses but are strategically significant for your particular competitive position.
Building Custom Intelligence Frameworks
Custom intelligence frameworks are not simply bespoke versions of standard research methodologies. They are designed around the specific strategic questions that matter to your organization and cannot be answered by data that was constructed to matter to everyone.
Effective proprietary frameworks typically integrate multiple research modalities: structured primary research, ethnographic and qualitative field work, competitive signal monitoring, and internal data analysis conducted through a strategic rather than operational lens. The integration layer is critical. Organizations that conduct primary research in isolation—without connecting findings to competitive context and internal performance data—frequently generate insights that are interesting but not actionable.
For U.S. companies operating in highly competitive verticals—consumer packaged goods, financial services, healthcare, technology—the development of custom intelligence frameworks often requires a fundamental reorientation of how the research function relates to strategy. Research cannot operate as a reporting service that delivers findings after strategic decisions have already been framed. It must function as a forward-facing capability that actively shapes the questions leadership is asking, not merely the answers they receive.
The Strategic Value of Contrarian Market Signals
Perhaps the most underutilized dimension of proprietary intelligence is the deliberate pursuit of contrarian market signals—data points and patterns that diverge from the consensus narrative embedded in mainstream industry research.
Contrarian signals are not the same as outlier data. Outliers may be noise. Contrarian signals are systematic divergences from consensus expectations that, upon investigation, reveal a coherent alternative interpretation of market dynamics. They are the early indicators that a category assumption is weakening, that a consumer behavior is shifting faster than aggregate surveys have captured, or that a competitive threat is forming in an adjacent space that industry reports have not yet classified as relevant.
Mass-market research providers are structurally disinclined to foreground contrarian signals. A finding that challenges the prevailing narrative of a category risks alienating the majority of subscribers who have built internal alignment around that narrative. The commercial incentive runs directly counter to the analytical obligation to surface uncomfortable data.
Organizations that develop the capacity to identify and interpret contrarian signals—through proprietary primary research, alternative data sources, and analytical frameworks not shared with competitors—gain access to a form of intelligence that syndicated research cannot provide by design.
From Consensus Consumer to Competitive Advantage
The strategic imperative here is not to abandon third-party research. Industry reports, syndicated data, and published market analyses retain genuine utility as baseline orientation tools. The imperative is to recognize their inherent limitations and invest in the proprietary intelligence capabilities that transform baseline orientation into genuine competitive differentiation.
U.S. enterprises that continue to treat syndicated research as the primary input to strategic planning are not making evidence-based decisions. They are making consensus-based decisions and labeling them evidence-based. That distinction matters enormously when the goal is to outperform competitors who are reading the same reports, drawing the same conclusions, and executing strategies that are, at their foundation, structurally identical.
The organizations that will define the next competitive cycle in their respective markets are those building intelligence architectures their competitors cannot access—not because they have larger research budgets, but because they have asked better questions and built the proprietary infrastructure to answer them.